Van Compare is a UK van insurance price comparison website. We share general information,
not personal recommendations.
Published: 02 Jun 2026 | Last reviewed: 22 Jul 2026 | Reviewed by: VanCompare Editorial Team
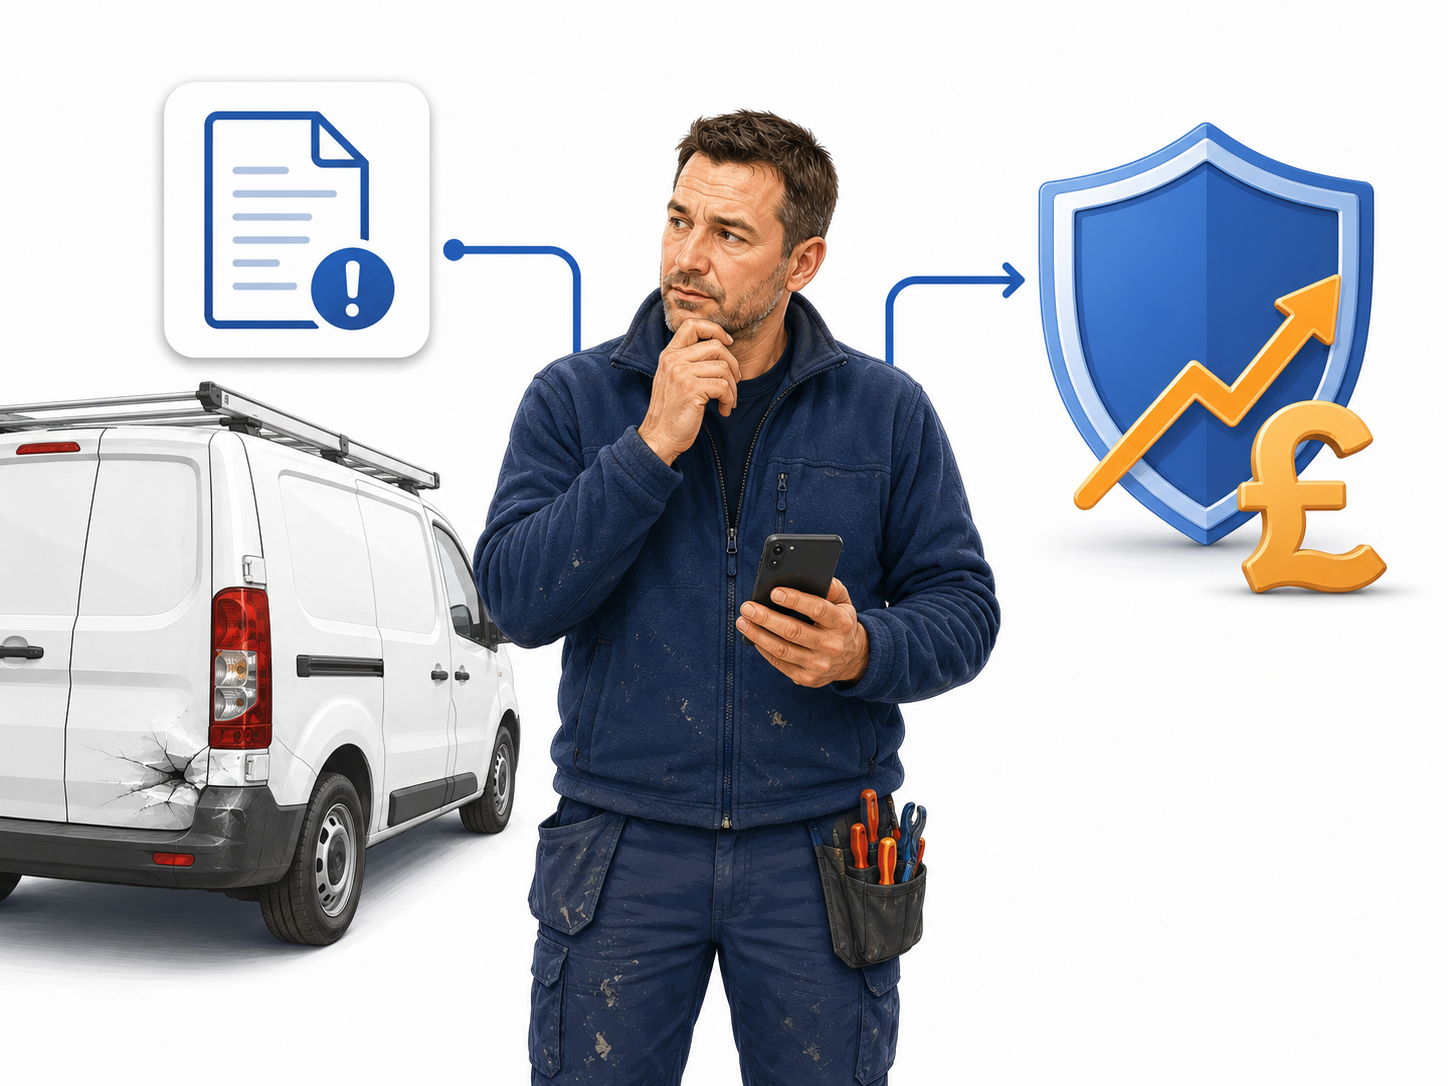
An at-fault claim can change your van insurance position quickly. Even if the damage is sorted and the claim is closed, the effect often carries on into renewal and future quotes.
That is because insurers do not just look at the van. They also look at what your recent claims history may say about future risk. A single at-fault claim does not mean you cannot get cover, but it often means higher prices, tighter underwriting, or fewer insurers willing to quote in the same way as before.
This guide explains what usually happens after an at-fault claim, how it can affect price and cover, and what van drivers can do next.
The short answer
After an at-fault claim, the most common outcomes are:
- a higher premium at renewal
- a reduced or lost no claims bonus if it was not protected
- fewer insurers willing to quote on the same terms
- higher excesses or tighter conditions in some cases
The exact effect depends on things like:
- how recent the claim is
- how expensive it was
- whether there was injury involved
- whether you have other claims or convictions
- how the van is used
So while an at-fault claim usually makes insurance harder or more expensive, it does not affect every driver in the same way.

What counts as an at-fault claim?
An at-fault claim does not always mean you were morally to blame in a simple everyday sense. In insurance terms, it usually means your insurer had to pay out and could not recover the money from someone else.
That can include obvious examples, such as:
- reversing into another vehicle
- hitting a wall or gate
- causing a collision in traffic
But it can also include cases where fault is disputed or where recovery from another party never happens.
That is why drivers are sometimes surprised to be told they had an “at-fault” claim even when the situation felt more mixed.
What usually happens to the price?
The most common result is that the price goes up.
Insurers generally see a recent at-fault claim as a sign that the chance of another claim may now be higher. That does not mean every insurer reacts in the same way, but it does mean the claim often changes the risk profile attached to you and the van.
The increase is not driven by one factor alone. Insurers may look at:
- the cost of the claim
- whether another vehicle, property, or injury was involved
- how recent it was
- whether it was a one-off or part of a pattern
- whether your van use is already high-risk, high-mileage, or business-heavy
A minor parking bump from several years ago may be treated more lightly than a recent and expensive road traffic claim involving injury or major repairs.
What happens to your no claims bonus?
If your no claims bonus is not protected, an at-fault claim will often reduce it.
That matters because no claims bonus can make a noticeable difference to van insurance pricing over time. Once that record takes a hit, the renewal can move for two reasons at once:
- the claim itself changes the risk picture
- the no claims discount may shrink as well
So some drivers feel the increase twice.
If the no claims bonus was protected, that may help preserve the discount, but it does not always stop the overall premium from rising. Protected no claims bonus does not usually mean “no pricing impact at all.” It usually means the discount level is less affected, rather than the claim being ignored completely. Our guide to no claims bonus for van insurance explains in more detail how protection works, where drivers often misunderstand it, and why a premium can still rise even when the discount itself is preserved.
Will all insurers still quote?
Not always.
After an at-fault claim, some insurers may still quote in a fairly normal way, especially if the claim was minor and your wider record is clean. But if the claim was recent, costly, or sits alongside other issues such as previous claims, points, or cancellations, mainstream options may narrow.
That is often where drivers move from a standard-market feel into a more non-standard one, even if only for a while.
This does not always mean specialist-only forever. It often just means the pool of comfortable insurers becomes smaller for a period.
Can the cover terms change as well as the price?
Yes.
Price is the most obvious change, but it is not the only one. After an at-fault claim, insurers may also change:
- the excess
- the willingness to include optional extras
- the appetite for certain types of use
- the willingness to cover additional drivers
- the level of flexibility around modifications or business activity
For example, a driver with a recent at-fault claim on a heavily used work van may find that one insurer is still willing to quote, but only with a higher excess or firmer underwriting.
That is why comparing only the headline premium can be misleading after a claim.
Does the size of the claim matter?
Usually, yes.
Insurers are likely to care not just that there was a claim, but also what kind of claim it was.
A lower-value claim with limited damage is usually different from:
- a claim involving injury
- a major repair bill
- a write-off
- a claim involving third-party costs
- a claim that arose in obviously risky circumstances
The more serious or expensive the claim, the more likely it is to change how future insurers see the risk.
Does it matter if the van is used for work?
Very much so.
With van insurance, usage always matters. If the van is used daily for work, deliveries, customer visits, tools, or commercial transport, the effect of an at-fault claim may feel sharper than it would for a lightly used private vehicle.
That is because insurers are not only pricing the driver. They are pricing the combination of:
- the driver
- the van
- the business use
- the mileage
- the environment the van operates in
So a recent at-fault claim on a heavily worked van may attract more concern than the same claim on a lower-mileage personal-use vehicle.
How long does an at-fault claim affect van insurance?
It often affects pricing for several years, though the strongest effect is usually while the claim is still recent.
Insurers tend to care most about what has happened in the recent past, especially where there is already another risk factor in the background. Over time, a cleaner record after the claim can help improve the picture again.
So the effect is rarely permanent in the same way forever, but it can stay relevant for long enough that it needs to be declared and priced around properly.
What should you do after an at-fault claim?
Once the claim itself is handled, the next smart steps are usually practical ones.
1. Be clear on how the claim was recorded
Make sure you understand whether it is being treated as at-fault and what was actually paid out.
2. Check your no claims position
Do not assume. Confirm whether it was reduced, protected, or affected in some other way.
3. Review the renewal carefully
Do not just look at the top-line number. Check:
- excess
- cover level
- class of use
- named drivers
- optional extras
4. Compare the market properly
After a claim, insurer appetite can vary more than usual. That means it is worth checking more than one route rather than accepting the first answer.
5. Fix any wider risk issues
If the van also has security weaknesses, driver declaration issues, or avoidable admin problems, now is the time to tighten them up.
How can you improve your position on future quotes?
You cannot erase an at-fault claim, but you can make the overall risk look stronger over time.
Things that usually help include:
- keeping a clean licence after the claim
- avoiding further claims where possible
- keeping mileage realistic and honest
- making sure the class of use is correct
- choosing a sensible van and setup
- improving overnight security
- comparing quotes rather than relying on one insurer’s view
This is not about “tricking” the premium down. It is about making sure the rest of the risk picture is as strong and accurate as possible.
FAQs
Will one at-fault claim stop me getting van insurance?
Usually not. One at-fault claim will often increase the price, but it does not normally stop you getting cover on its own. The wider picture still matters.
Does an at-fault claim always reduce no claims bonus?
Not always. If your no claims bonus is unprotected, it will often be reduced. If it is protected, the discount may be preserved, though the premium can still rise.
Do insurers care how expensive the claim was?
Yes, often. A recent and costly claim is usually treated more seriously than a smaller one with limited damage.
Will all insurers still quote after an at-fault claim?
Not always. Some may still quote normally, while others may step back or offer different terms, especially if the claim is recent or sits alongside other risks.
How long will an at-fault claim affect my van insurance?
It can affect future quotes for several years, with the biggest impact usually while the claim is still relatively recent.
When should you use a broker or wider comparison route?
If the at-fault claim is recent, expensive, or sits alongside other issues, it often helps to look beyond a very narrow mainstream route.
That is where it helps to understand how insurers usually view drivers with more complex records, and where comparison sites, brokers and direct insurers each fit when the risk is less straightforward. Our guide to high risk van insurance explains how cover usually works for drivers with claims, convictions or cancelled policies, while our comparison of where to get van insurance quotes in the UK looks at the strengths and limits of comparison sites, brokers and direct insurers.
Next steps
If you have had an at-fault claim, the key is not to panic and not to assume every insurer will react the same way.
Check how the claim was recorded, understand what happened to your no claims bonus, review the renewal carefully, and compare properly before accepting the first price you see. An at-fault claim often makes cover more expensive, but the right setup still matters just as much as the headline premium.
If you are ready to compare again, start here.
VanCompare Editorial Team
The VanCompare Editorial Team produces clear, practical guidance on UK van insurance and related topics. We work with FCA authorised insurance providers and use insurer information where relevant to explain cover in plain English and help drivers make informed decisions.
- Where relevant, our content is checked against publicly available UK guidance and information from sources such as the FCA and GOV.UK to help keep it accurate and up to date.
- This content is for general information only and is not financial advice.
- Learn more about our editorial standards and transparency on the VanCompare TrustHub.