Van Compare is a UK van insurance price comparison website. We share general information,
not personal recommendations.
Published: 22 Dec 2025 | Last reviewed: 22 Jul 2026 | Reviewed by: VanCompare Editorial Team
For many van drivers, the no claims bonus feels like a crucial lever behind every quote and its pricing. It is not a pot of money or a separate policy, but it can make a big difference to what you pay.
This guide explains what a no claims bonus actually is, how to apply it, what happens when you claim, how protection works, and how to think about it when you compare van insurance quotes.

What a no claims bonus actually is
A no claims bonus (NCB), also called a no claims discount, is a discount on your van insurance premium that builds up for each full policy year you complete without a claim that affects the bonus.
In close to all cases, only the policyholder earns NCB on a policy. Named drivers do not build their own separate NCB on that policy.
If you cancel mid-term or switch providers before a full year has run, that year will usually not count towards your NCB. If you switch or cancel before 12 months, you usually do not get credited with that year.
Many insurers treat van NCB as separate from any car NCB you have, because van risks and usage patterns are different. Some may let you move a bonus across, but it is never automatic, and a lot of providers will not accept NCB earned on a motorcycle at all.
How insurers count “claim-free” years
Insurers do not all count in exactly the same way, but the usual pattern looks like this:
- You complete a full year on cover.
- If there has been no claim that reduces your NCB, the insurer adds one year to your total.
- At renewal, they put you into a higher discount band based on that new total.
That does not always mean the total premium will fall. If base rates or other rating factors have gone up, you can see a higher discount applied to a higher starting price and still end up paying more.
Typical maximum NCB levels
Most van insurers have a maximum NCB level, often in the region of 5 to 9 years. After that point you might still see “10 years+” on your documents, but the extra years do not always trigger extra discount.
That does not mean long claim-free driving is wasted. A long, clean history can still influence:
- Whether the insurer will offer cover at all
- How they view any new claim you do have
- How sharply your premium reacts if something goes wrong
Using your NCB across vehicles and policies
An NCB is a single set of years that can only be applied to one vehicle at a time. You cannot split it, and you cannot use the same set on two live policies at once.
A simple example:
- You insure a van for 5 years without a claim that affects NCB. You now have 5 years NCB on that policy.
- You buy a second van and take a new policy. Unless you formally move the NCB, the new van will usually start on 0 years NCB.
- If both policies run to their full term with no NCB affecting claims, next year the original van would show 6 years and the newer van 1 year.
If you then sell the older van, you might want to put the 6 years NCB onto the newer van. The crucial point is:
- You cannot add the 6 and the 1 together and call it 7 years.
- You must choose which set is applied. One set is used; the other is left unused.
Unused NCB does not always disappear straight away. Many insurers will treat NCB as valid for a period (commonly up to two years) after it was last in use. After that, it can be treated as lapsed. Some providers work to a shorter timescale, so you cannot rely on unused NCB staying available indefinitely.
If you are thinking about changing vehicles or changing how many vans you run, it is worth checking:
- Which policy your strongest NCB is attached to right now
- How long your provider will treat unused NCB as valid
- What proof they need if you want to use it later
What happens to your NCB if you claim
Fault vs non fault claims
When you claim, the insurer normally asks one key question for NCB purposes:
Was this a fault, non fault, or split-liability claim?
- Fault claim: the insurer expects to pay out and cannot recover all costs from another party.
- Non fault claim: another identified insurer accepts responsibility and reimburses the costs.
- Split or partial fault: liability is shared in some proportion.
In many cases, only fault or partial fault claims reduce your NCB. A clear non fault claim, where your insurer recovers everything from the other side, often leaves your NCB intact.
Even non fault claims, however, can still influence the base price. From an underwriting point of view, a claim is still an event, and frequent non fault claims may suggest higher overall exposure, even if your NCB years remain at the same level.
Step back scales and full resets
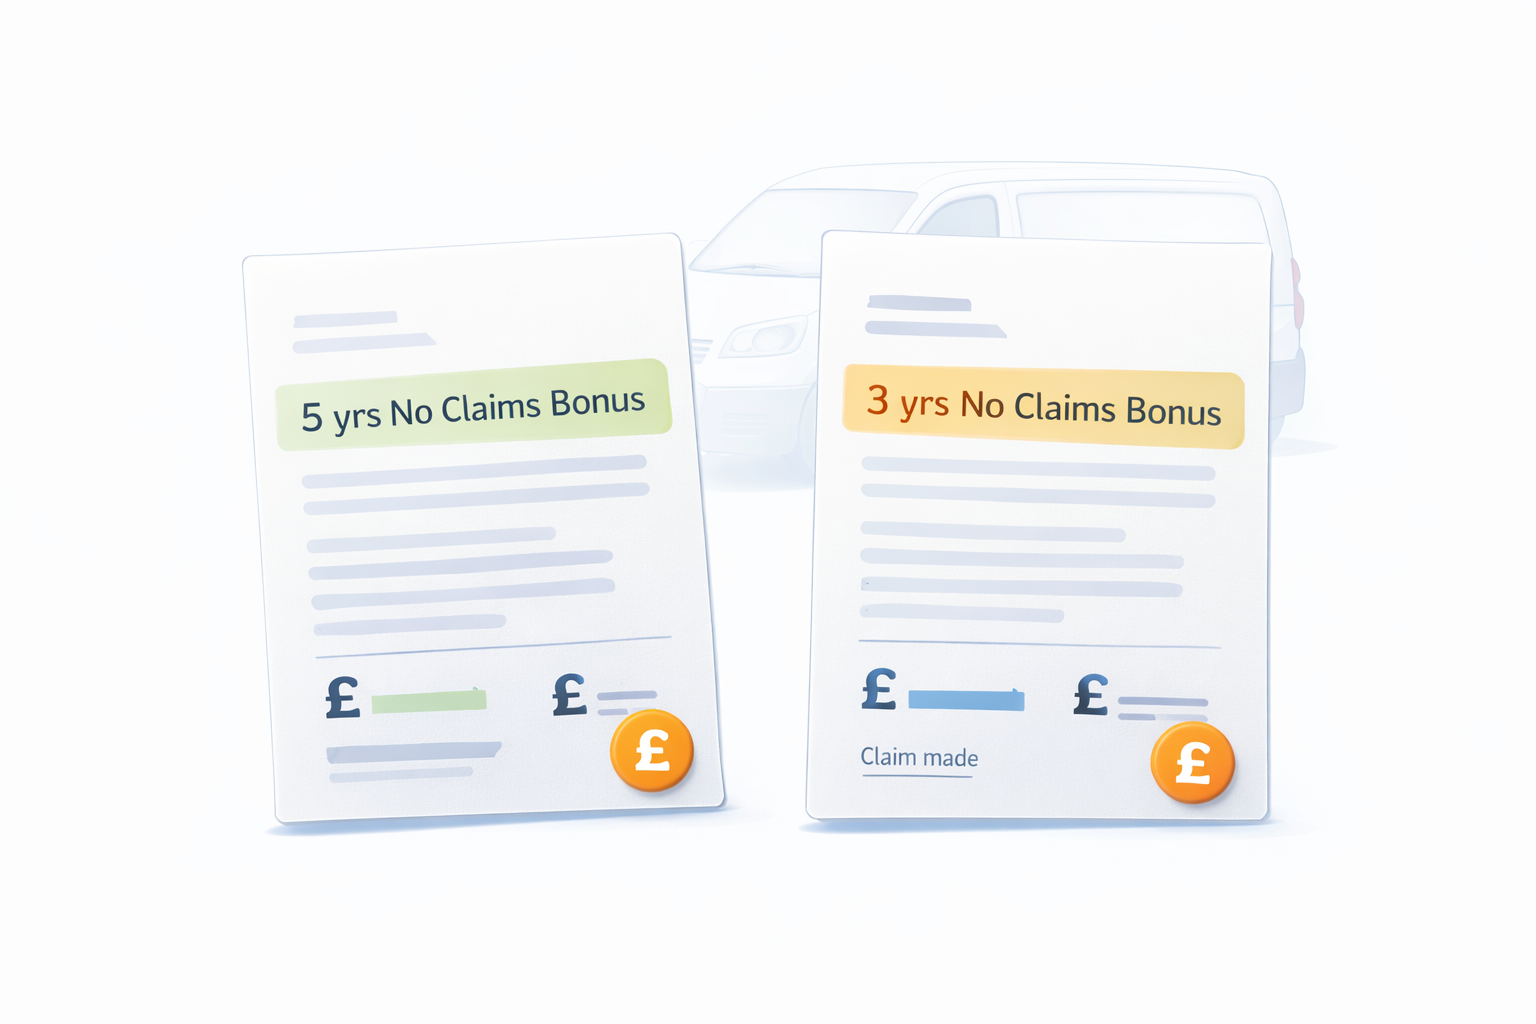
Most insurers use a “step back” scale to decide what happens to your NCB after a fault claim. A simple example pattern might be:
- 5 years NCB → 3 years after one fault claim
- 3 years NCB → 1 year after one fault claim
- Two claims in a short period → a further step back, or reset to zero
With some policies, a single fault claim can mean the loss of your entire NCB. The exact treatment is set by each insurer’s own scale.
Protected no claims bonus explained
What protection does and does not do
Protected NCB is an optional add-on that tries to soften the impact of one or more claims on your bonus years.
In simple terms, protection usually means:
- A set number of claims in a period are allowed without dropping your NCB years all the way back.
- Your documents continue to show the same NCB years you had before the claim, as long as you stay within the rules of the protection.
However, protection does not:
- Freeze your premium at the old price
- Stop the insurer from taking the claim itself into account
- Guarantee that other insurers will treat your NCB the same way if you move to them later
For many insurers, the working assumption is:
- The underlying premium reflects your recent claims record, vehicle, use and other rating factors.
- The NCB then changes the size of any discount applied to that figure.
Some providers treat NCB slightly differently in their pricing models, but the practical effect is the same: building NCB can help reduce what you pay, and losing it can mean you pay more, even if other factors are moving at the same time.
Why your premium can still go up after a claim
Even with protected NCB, your premium can rise after a claim because the base view of your risk has changed. A protected discount can still be applied to a higher starting price.
So you may see:
- The same NCB years listed on your documents
- A higher overall renewal price
- Tighter terms such as higher excess or conditions
Protected NCB can still be useful, because it can leave you in a better position than you would have been without it, but it is not a promise that prices stay flat.
Common myths about NCB for van drivers
“My NCB is the same with every insurer”
In practice, each insurer has its own rules about:
- How many years they recognise
- How they treat old or partial years
- How they step back after claims
- Which vehicle types they will accept transferred NCB from
- Which countries they will accept NCB from and on what terms
Most will accept a valid NCB letter from another insurer, but they might cap the years at their own maximum or map them to their own scale. A “14 years NCB” on one renewal notice will not always show as 14 with every new provider.
Some insurers are more open to NCB earned in other European countries, as long as the proof is clear and in English. Others will not accept overseas NCB at all.
“Protected NCB means my price will not rise”
Protection helps preserve your bonus years, not your renewal figure.
After a claim you may still see:
- A higher base premium
- Different treatment of your risk if you move insurer
- Extra terms such as higher excess or tighter conditions
Protected NCB can leave you better off than if your bonus had been stepped back, but it does not ring fence your premium.
“Named drivers build their own NCB on my policy”
Most of the time, the no claims bonus belongs to the policyholder, not to every named driver.
Named drivers can benefit from a clean record when they later take out their own policy, but they do not usually take the policyholder’s NCB with them. A few specialist products may treat long term named drivers differently, but this is very uncommon and should never be assumed.
How to think about NCB when you compare quotes
When you compare van insurance, NCB is one lever among several. It sits alongside:
- Your level of cover (third party, third party fire and theft, or comprehensive)
- Your voluntary excess
- Your class of use, mileage and vehicle details
Increasing your voluntary excess can lower what you pay, but it also increases how much you would face if you claim. Your NCB then applies on top of however the insurer sets the base price.
It can help to think in layers:
- First, pick a realistic cover level and class of use for the way you actually work.
- Second, check your NCB years and whether protection is available and affordable.
- Third, adjust excess within a range you could genuinely pay on a bad day.
Then you can compare like with like, instead of chasing a headline price that only works because something important has been stripped out.
Paying extra to protect your NCB can make more sense when:
- You have built several years of bonus and want to avoid a big step back from one claim.
- Your van is central to your income and you expect to stay insured for the long term.
- You know that restarting at low or zero NCB would make future premiums harder to manage.
It can be less useful if you are new to van insurance and only have one or two years so far, or if you are not sure how long you will keep the van or stay in that line of work.
You are not buying protection from price changes; you are buying some protection from losing the discount level you have built up.
No claims bonus FAQs
Can I move my car NCB to a van policy?
Sometimes you can, but it is not guaranteed. Some insurers will accept private car NCB on a van policy, others will not, and some may only accept it once and then treat it as “used.” NCB from motorcycles is often not accepted for vans. You should not assume that car and van NCB are interchangeable without checking the insurer’s rules.
Does a windscreen claim affect my no claims bonus?
On many policies, a glass-only or windscreen claim does not reduce your NCB, but it can still appear on your claims history. Some insurers do treat certain glass claims as affecting NCB. The safest approach is to read your policy wording or ask your broker before assuming it has no effect.
Can I have protected NCB on a company van?
In some cases, yes. Whether you can protect NCB on a company van depends on the insurer, how the policy is set up, and who is the policyholder. Some commercial van policies offer NCB protection as an option, others do not. If you insure vans in a company name, it is worth asking specifically whether an NCB is earned and whether it can be protected.
Note: This is general information, always check your policy wording and insurer rules.
Next steps if you rely on your no claims bonus
If your no claims bonus has built up over several years, it is worth treating it as something to actively look after, not just a line on your documents.
You can:
- Make sure you know exactly how many years NCB you have and where it is held.
- Check how your current insurer treats step backs, resets and windscreen claims.
- Think ahead if you plan to add or replace vans, so you know which policy will carry your main NCB.
- Ask a broker or provider to explain how NCB and protection options work on any new quote, rather than guessing based on car insurance.
A clear view of your NCB, and how each insurer treats it, makes it easier to compare quotes fairly and avoid surprises at renewal or after a claim.
VanCompare Editorial Team
The VanCompare Editorial Team produces clear, practical guidance on UK van insurance and related topics. We work with FCA authorised insurance providers and use insurer information where relevant to explain cover in plain English and help drivers make informed decisions.
- Where relevant, our content is checked against publicly available UK guidance and information from sources such as the FCA and GOV.UK to help keep it accurate and up to date.
- This content is for general information only and is not financial advice.
- Learn more about our editorial standards and transparency on the VanCompare TrustHub.