Van Compare is a UK van insurance price comparison website. We share general information,
not personal recommendations.
Published: 15 Dec 2025 | Last reviewed: 22 Jul 2026 | Reviewed by: VanCompare Editorial Team
For many small firms, the real question is not “do we need van insurance” but “what setup makes sense for the way we actually work.”
Two options come up again and again:
- Any driver van insurance
- Named driver van insurance
On paper, any driver looks simple. Anyone you choose can use the van. In practice, the right choice depends on how your staff, vehicles and risk really look day to day.
This guide explains how each option works, how insurers think about them, and what small firms should weigh up before they decide.

What does named driver van insurance mean?
With named driver van insurance, you list the specific people who are allowed to drive the van, and the insurer prices the policy around those named drivers. Some insurers will only allow up to a certain number of named drivers, so larger teams may find this harder to manage on one policy.
A simple setup might look like:
- One main user (for example a tradesman who uses the van most days)
- One or two additional drivers (such as another director or a trusted employee)
Key points:
- Only the drivers named on the policy are covered to drive.
- Their age, licence history, claims and convictions all feed into the price.
- If you want to add or remove someone, you usually need to ask the insurer or broker to amend the policy.
Named driver cover often suits firms where:
- Each van has a clear main user.
- You know exactly who should be driving which vehicle.
- You do not need constant, last minute swaps between lots of drivers.
What does any driver van insurance mean?
Any driver van insurance usually means that anyone who meets the policy rules can drive the van, without each person being named one by one.
Common examples:
- Any driver over 25 with a clean licence.
- Any driver over 30 with a clean licence.
The exact wording varies by insurer. Some want every driver to be within a certain age band or have a minimum licence length. In practice, many any driver policies still have quite strict rules on who is allowed to drive. For example, an insurer might only accept drivers over 25 who have held a full UK licence for at least two years and have no recent claims or convictions.
Any driver does not mean any type of work
It is also important to remember that any driver cover does not overwrite the class of use on the policy. If the policyholder has business use for carriage of own goods in a construction trade, many insurers will only see that van as covered for that trade. Other drivers who meet the age and licence rules might still be allowed to drive, but often only for social, domestic and pleasure use. Using the van for a different business, such as courier work or a second trade, without the right class of use can cause problems if a claim is checked against what was declared at the start.
It is always important to understand exactly who can and cannot drive under an any driver policy.
This type of cover is often used when:
- Vans are shared between teams on different shifts.
- You have relief drivers who cover sickness and holidays.
- You run a small fleet where flexibility matters more than linking each van to one driver.
Because the insurer takes on more uncertainty about who will be behind the wheel, any driver cover is often more expensive than a comparable named driver setup.
How insurers look at small firms using vans
Insurers have a few simple questions in the background:
- Who will actually drive these vans most of the time?
- How many people might drive them over a year?
- How easy will it be to manage standards, training and checks?
- If something goes wrong, is it clear who was allowed to drive and why?
For small firms, that often splits into two broad patterns:
- Driver-centric use
- Each van is “owned” in practice by one tradesman or employee.
- Others might drive sometimes, but there is a clear main user.
- Pool-van use
- The van is more like a shared tool.
- Different staff use it on different days or shifts.
- The firm cares more about keeping work moving than about one driver per van.
Named driver cover fits better with the first pattern. Any driver fits better with the second, as long as the firm can prove it is on top of who is allowed to drive and that licence checks are done.
When named driver van insurance can work better
Named driver cover often makes sense when:
- You run a small trade or service firm with one or two vans.
- Each van has a clear, regular user.
- You do not need constant staff rotation.
Possible advantages:
- Price: Insurers can price more precisely around known drivers, which can be cheaper than a broad any driver basis, especially if your team is experienced and claims-light.
- Control: It is clear who is meant to drive each vehicle. That can make it easier to manage standards and responsibility.
- Simpler claims story: If a claim happens, it is usually straightforward to show that the driver was named and allowed to be in that van.
Things to watch:
- You need a process for adding or removing drivers when staff join, leave, or change roles.
- Letting a non-named friend or temp “just nip out” in the van can cause problems if a loss occurs.
When any driver van insurance can work better
Any driver cover may be more suitable where:
- You have several staff who regularly swap vehicles.
- Shifts or routes change daily.
- You cannot easily tie each van to one main driver.
- There are too many potential drivers of the vehicle for a named driver policy
Possible advantages:
- Flexibility: If a driver is off sick or a route changes, another eligible driver can step in without mid-term policy changes.
- Less admin on small changes: You are not adding and removing names each time rotas move around, as long as new drivers fit the policy rules.
- Better match for genuine pool-van use: Trying to force a shared van setup into a named driver policy can create confusion if staff use vehicles outside the list.
Things to watch:
- Any driver cover usually costs more than naming a small set of known drivers.
- You still need good records of who drove what and when, for both risk and tax reasons.
- You must pay attention to the age, experience and licence status of anyone allowed to drive, even if they are not named one by one.
Mixed or hybrid setups
In between named driver and any driver, some insurers will offer a mix of the two. A common pattern looks like this:
- Any driver over 25, with at least two years on a full UK licence and no recent claims or convictions
- Plus one or more named drivers who fall outside those rules
This can help if most of your team fit the standard any driver criteria, but one person does not. By naming that driver on the policy, the insurer can rate them more accurately because they have the full details. The rest of the team can still use the van under the broader any driver terms, within the age and licence limits set out on the schedule.
If you think you need this kind of flexibility, it is worth asking whether a mixed setup is an option rather than assuming you must choose a pure named driver or pure any driver policy.
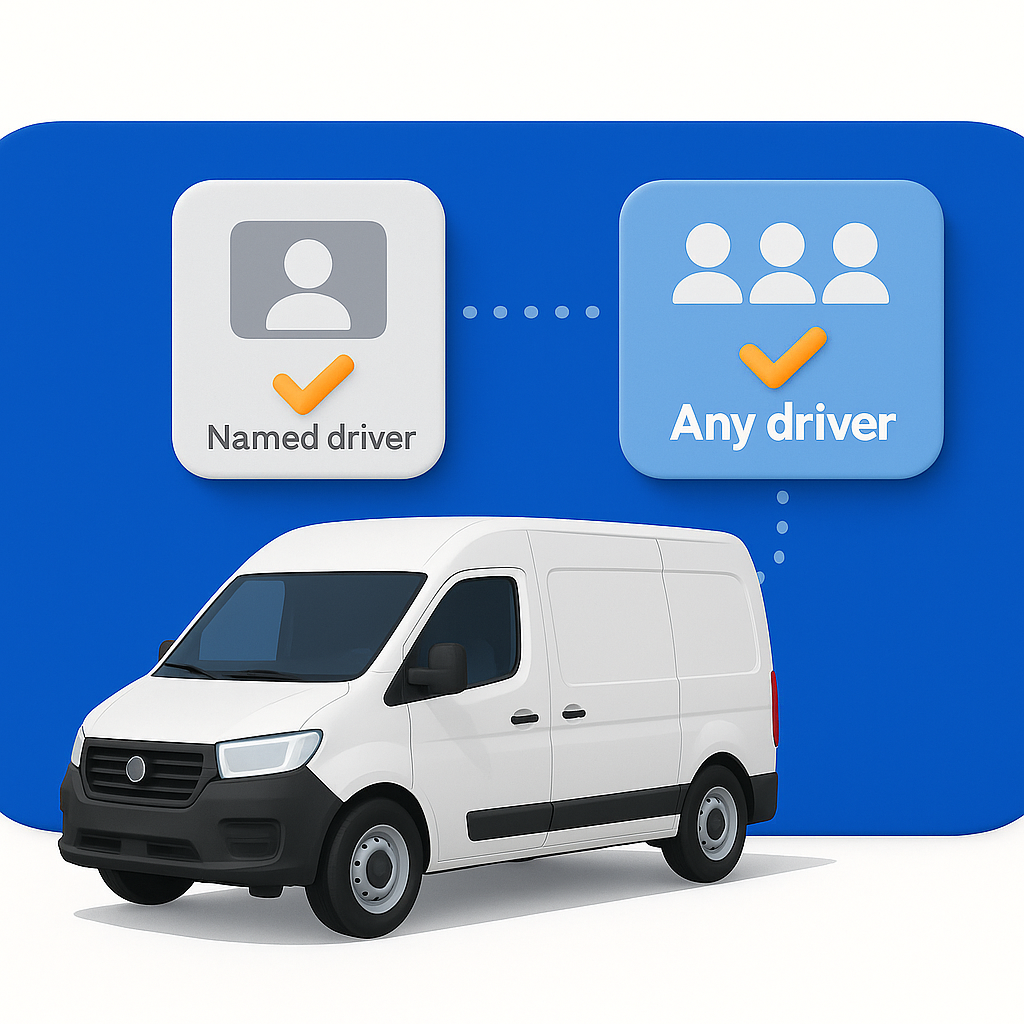
Cost, risk and control: simple comparison
For small firms, the trade-offs are mostly about price, control and how you work day to day.
Named driver van insurance
- Price: often lower if you have a small, stable group of experienced drivers.
- Control: high. Only listed drivers can use the van.
- Admin: you need to keep the driver list updated.
- Risk of misuse: lower if you stick to the list, but there is temptation to “lend” the van.
Any driver van insurance
- Price: often higher, as the insurer takes on more uncertainty.
- Control: flexible, but you must manage who fits the criteria.
- Admin: less about adding names, more about licence checks and internal rules.
- Risk of misuse: higher if staff think “anyone can drive” without reading the policy limits.
Common mistakes small firms make
A few patterns come up a lot across small businesses:
- Assuming any employee is covered: Even with any driver cover, the policy may only allow drivers over a certain age, with a minimum licence length, and within set limits on points or claims.
- Letting staff “try a van” before checks are done: If someone has undisclosed bans or serious convictions, an unplanned test drive could cause problems later.
- Using named driver cover for a genuine pool van: If lots of people use the van but only a few are named, the setup and reality may not match.
- Assuming an any driver policy allows any trade or side job: The fact that several people can drive the van does not mean they can all use it for their own business. Many insurers treat the policyholder’s main trade as the only business use allowed, unless a wider class of use has been agreed.
- Not updating named driver lists: When staff leave or roles change, the driver list can lag behind, which is risky if the policy is later reviewed.
- Letting family use company vans informally: Out of hours use by friends or relatives often falls outside the intended risk, unless it is clearly allowed and set up that way.
Practical checks before you choose
Before you decide between any driver and named driver, it can help to ask:
- How many people genuinely need to drive each van in a normal month?
- Are our vans really linked to people, or are they shared tools?
- How often do rotas and routes change?
- Are we ready to keep driver lists updated if we go named driver?
- Are we ready to run licence checks and simple rules if we go any driver?
If you can answer those clearly, you are in a better place to discuss options with a broker or on a comparison site.
Working with brokers and comparison sites
For some small firms, a standard comparison site quote will be enough to show the difference between any driver and named driver premiums.
For others, especially where there is a mix of:
- Younger staff
- Claims or convictions
- Higher risk work such as courier or night delivery
it can help to speak with an FCA authorised broker as well. They can ask more detailed questions about how your vans are used, who drives them, and what sort of internal controls you have, then reflect that in the type of cover suggested.
The important piece is consistency:
- Describe your setup the same way wherever you get quotes.
- Do not downplay how many people really drive or how often they change.
- Be clear if you want any driver only for a narrow group, such as over-25s with clean licences.
Any driver vs named driver van insurance FAQs
Is any driver van insurance always more expensive than named driver cover?
Often it is, because the insurer knows less about exactly who will be driving. That said, there are cases where a named driver policy with very young or high risk drivers can come out at a similar or higher cost. The only way to see the difference for your firm is to get quotes on the same day using honest, matching details.
Can I mix named drivers and any driver on the same van policy?
Some policies will allow a blend, such as named drivers plus any driver over a certain age, or any driver for business use and tighter rules for social use. The exact options depend on the insurer. If you think you need a mixed setup, it is worth asking a broker or provider to explain what their wording allows.
Are employees automatically covered to drive a company van?
No. Cover usually depends on the wording of the policy: either being named on a named driver list, or fitting the age and licence rules on an any driver policy. Assuming that “staff are covered” without checking can cause surprises if a loss happens and the driver does not meet those conditions.
Can staff use a company van for personal trips under any driver cover?
Not automatically. Personal and family use needs to be allowed by both the insurer and the employer. Some policies include social and commuting use, others restrict cover to business use only. There may also be tax implications where personal use is allowed. It is safer to check the wording and, if needed, take advice before treating a company van as a general pool car.
What records should a small firm keep if it uses any driver van insurance?
Simple, clear records help. Many firms keep a log of who is allowed to drive, copies or checks of driving licences, and basic booking or key sign-out records for each van. This does not need to be complex, but having a trail of who drove what and when can support both safety management and any later claim discussions.
Next steps for small firms deciding between any driver and named driver cover
Choosing between any driver and named driver van insurance is not about one label being “better.” It is about matching the policy to how your firm really uses its vans, and then running basic controls around that setup.
You can:
- Map out who drives each van, how often, and how predictable that pattern is.
- Think through how much flexibility you genuinely need.
- Decide whether you would rather manage named driver lists, or licence checks within a wider any driver rule.
- Compare quotes for both options using the same honest information about drivers and use.
- Speak with an authorised broker if your mix of staff and work is more complex or if online panels are limited.
Once you understand your own pattern and have seen how the price and terms differ, it becomes easier to choose a structure that feels fair, manageable, and aligned with how you actually run the business.
VanCompare Editorial Team
The VanCompare Editorial Team produces clear, practical guidance on UK van insurance and related topics. We work with FCA authorised insurance providers and use insurer information where relevant to explain cover in plain English and help drivers make informed decisions.
- Where relevant, our content is checked against publicly available UK guidance and information from sources such as the FCA and GOV.UK to help keep it accurate and up to date.
- This content is for general information only and is not financial advice.
- Learn more about our editorial standards and transparency on the VanCompare TrustHub.